
The Housing Market Is Turning a Corner Going into 2026After several years of high mortgage rates and hesitation from buyers, momentum is quietly building beneath the surface of the housing market.

Dated: May 5 2025
Views: 5
Saving up to buy a home can feel a little intimidating, especially right now. And for many first-time buyers, the idea that you have to put 20% down can feel like a major roadblock.
But that’s actually a common misconception. Here’s the truth.
Unless your specific loan type or lender requires it, odds are you won’t have to put 20% down. There are loan options out there designed to help first-time buyers like you get in the door with a much smaller down payment.
For example, FHA loans offer down payments as low as 3.5%, while VA and USDA loans have no down payment requirements for qualified applicants, like Veterans. So, while putting down more money does have its benefits, it’s not essential. As The Mortgage Reports says:
“. . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . . the 20 percent down rule is really a myth.”
According to the National Association of Realtors (NAR), the median down payment is a lot lower for first-time homebuyers at just 9% (see chart below):
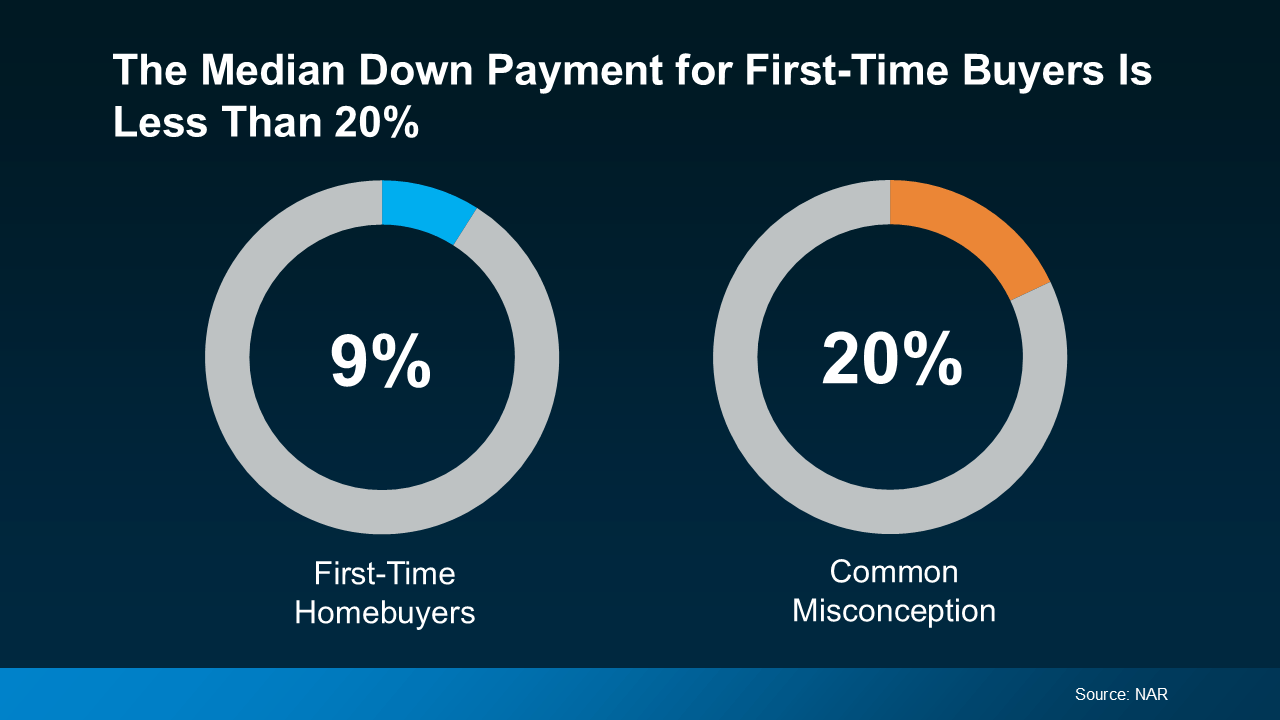 The takeaway? You may not need to save as much as you originally thought.
And the best part is, there are also a lot of programs out there designed to give your down payment savings a boost. And chances are, you’re not even aware they’re an option.
Believe it or not, almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% actually use it (see chart below):
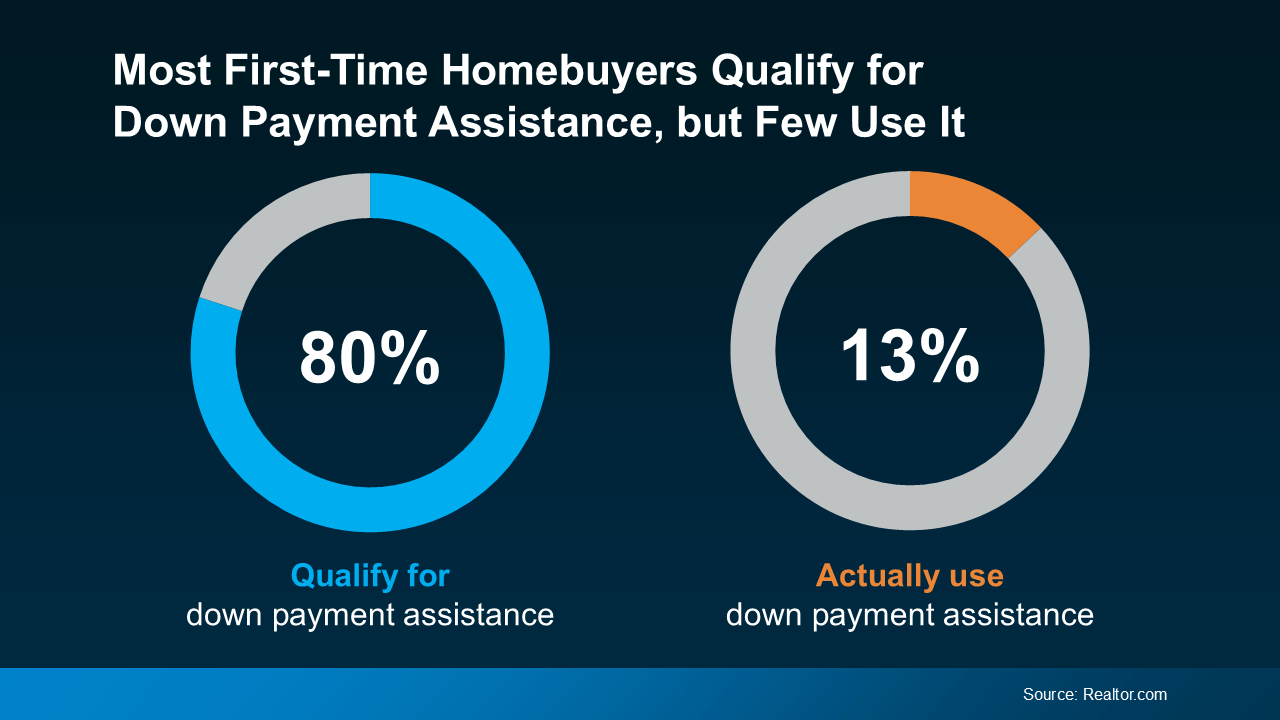 That’s a lot of missed opportunity. These programs aren’t small-scale help, either. Some offer thousands of dollars that can go directly toward your down payment. As Rob Chrane, Founder and CEO of Down Payment Resource, shares:
“Our data shows the average DPA benefit is roughly $17,000. That can be a nice jump-start for saving for a down payment and other costs of homeownership.”
Imagine how much further your homebuying savings would go if you were able to qualify for $17,000 worth of help. In some cases, you may even be able to stack multiple programs at once, giving what you’ve saved an even bigger lift. These are the type of benefits you don't want to leave on the table.
Saving up for your first home can feel like a lot, especially if you’re still thinking you have to put 20% down. The truth is that’s a common myth. Many loan options require much less, and there are even programs out there designed to boost your savings too.
To learn more about what’s available and if you’d qualify for any down payment assistance programs, talk to a trusted lender.
Pennsylvania, Maryland and New York licensed Real Estate Broker and RealtorYour Trusted Real Estate Partner in Pennsylvania, Maryland, and New YorkAs a licensed Real Estate Broker and Realtor, John an....
The Housing Market Is Turning a Corner Going into 2026After several years of high mortgage rates and hesitation from buyers, momentum is quietly building beneath the surface of the housing market.
Thought the Market Passed You By? Think Again.If you stepped back from your home search over the past few years, you’re not alone – and you’re definitely not out of options. In,
Why Some Homes Sell Quickly – and Others Don’t Sell at AllA few years ago, inventory hit a record low. Just about anything sold – and fast. But now, there are far more homes on the
The Reason Homes Feel Like They Cost So Much (It’s Not What You Think)Scroll through your feed and you’ll see plenty of finger-pointing about why homes cost so much. And according to a
 The data relating to real estate for sale on this web site comes in part from the Internet Data Exchange of the Greater Lehigh Valley REALTORS®. Real Estate listings held by brokerage firms (licensees) other than #firm are marked with the IDX logo and detailed information about them includes the name of the listing brokers.
The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers
may be interested in purchasing.
Data last updated September 21, 2026 12:27 PM UTC
Show More...
 ©2026 Georgia Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may
be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 12:19 PM UTC
Show More...
 The data relating to real estate for sale on this web site includes listings held by MLS-IDX Participants of the Internet Data Exchange program of the Multiple Listing Service of the Pocono Mountains Association of Realtors®. Listings marked with the Internet Data Exchange logo are not necessarily the listings of the owner of this web site. All listing data is the copyrighted property of the aforesaid Association and its MLS-IDX Participants with all rights reserved. The information contained
herein is believed to be accurate, but no warranty as such is expressed or implied.
Show More...
 © BRIGHT, All Rights Reserved
Information Deemed Reliable But Not Guaranteed
The data relating to real estate for sale on this website appears in part through the BRIGHT Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which
participates, and is provided by BRIGHT through a licensing agreement.
The information provided by this website is for the personal,
non-commercial use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data last updated: September 21, 2026 10:33 AM UTC
Some properties which appear for sale on this website may no longer be available
because they are under contract, have Closed or are no longer being offered for sale.
Some real estate firms do not participate in IDX and their listings do not appear on this website. Some properties listed with participating firms do not appear on this website at the request of the seller.
Show More...
 Luzerne County Association of REALTORS® (LZCAOR) All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 12:24 PM UTC
 Susquehanna Valley Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 12:29 PM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than The Brokers Realty Group Limited may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 12:23 PM UTC
Show More...
